
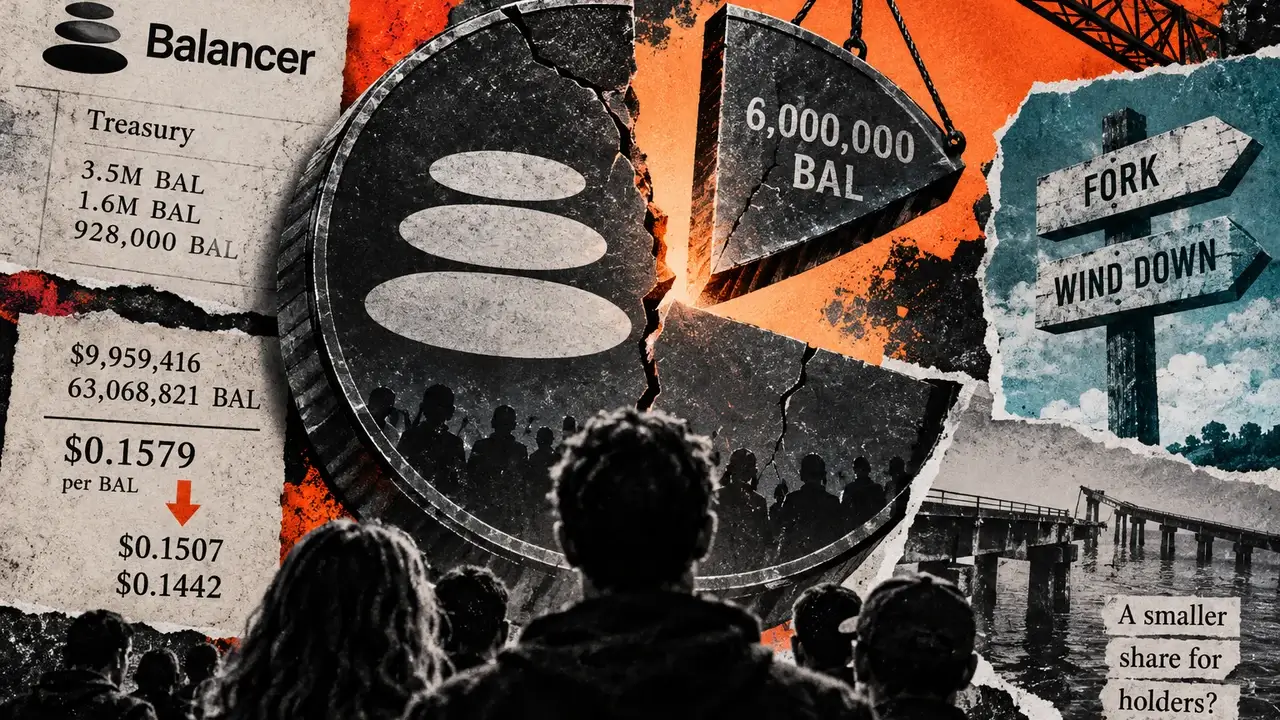
MAXYZ, a group of former Balancer contributors, is asking for up to 6 million currently non-circulating BAL to seed a successor protocol. If the granted tokens reach other eligible holders before Balancer’s proposed wind-down redemption snapshot, the same treasury would be divided among more BAL. In exchange, MAXYZ proposes a contingent allocation from a future fork to the Balancer treasury, an asset with no realized value today.
The fork proposal, posted Sept. 20 and expanded in a Sept. 23 FAQ, sits beside a separate wind-down plan to let BAL holders burn their tokens for a pro rata share of the DAO’s remaining assets. Neither forum proposal by itself transfers tokens, changes pool operations or gives the fork rights to code. The financial question for an old holder is how much of the grant would become redeemable, and whether a possible future stake in the fork compensates for a smaller share of the old treasury.
What six million BAL would change
MAXYZ identifies about 3.5 million BAL in the treasury, 1.6 million in a Balancer Labs fundraise safe and 928,000 in a Labs team safe as its proposed seed. Its Sept. 23 FAQ proposes taking half the grant upfront and the rest, up to the same cap, after tetuBAL holders have been paid because those claims may draw on the same non-circulating supply.
MAXYZ says the fork’s own treasury would be barred from redeeming against Balancer’s treasury. That restriction would not necessarily follow tokens sold or transferred to other holders. The wind-down plan fixes the redeemable supply at the opening snapshot, proposed for the end of May 2027, and says BAL leaving an excluded address after that snapshot would not become eligible. How much granted BAL might enter eligible hands beforehand remains unknown.
A Sept. 20 update to the wind-down proposal gives a dated reference point. Marcus said an unaudited on-chain measurement taken Sept. 18 found $9,959,416 in non-BAL assets available for distribution against 63,068,821 redeemable BAL. At the prices used then, that works out to about $0.1579 for each eligible BAL. Holding that asset value and all other eligibility rules fixed, 3 million additional redeemable BAL would lower the illustration to about $0.1507 per token. If all 6 million became eligible, it would fall to about $0.1442, roughly 8.7% below the original per-token figure.
Those are scenarios, not promised redemption prices. The grant would be staged, the amount ultimately circulating is unknown, and the wind-down ballot would choose whether tetuBAL holders receive 50% or 100% of the BAL behind their permanent lock. The assets and denominator would be measured again at the audited opening snapshot.
The figures also have different boundaries. KPK reported that the Balancer portfolio it managed rose from $8.63 million at the end of July to $9.59 million at the end of August. Marcus’s later $9.96 million illustration includes assets across more DAO positions and is net of the wind-down budget held outside that base. Neither KPK’s managed portfolio nor the September inventory fixes what holders would receive in 2027. The wind-down plan also excludes assets recovered for liquidity providers affected by attacks from the BAL-holder distribution.
MAXYZ offers a different potential return: if the fork has a token generation event or another liquidity or exit event, 10% of its fully diluted token supply or equivalent value would be allocated to the Balancer treasury. That is a proposed, conditional right. There is no realized fork payment to add to today’s redemption calculation.
A longer exit for partners
Under Marcus’s amended plan, pausable pools would move to withdrawals only on Oct. 30. Partners requesting an extension for a v3 pool by Oct. 16 could keep that pool live until Nov. 30. MAXYZ wants vaults and pools to remain unpaused until the end of the second quarter of 2027, unless an emergency requires action. The difference matters to partners that use Balancer’s pool designs and need time to decide where liquidity can go.
The public support is specific but short of a migration commitment. A Rocket Pool Incentive Management Committee member wrote in the MAXYZ forum thread, explicitly in a personal capacity, that moving some liquidity to a fork was realistic if security and migration paths worked. Royco’s forum account supported MAXYZ and said its Royco Day product uses Balancer v3 E-CLPs for secondary liquidity. Neither statement sets a quantity or obliges either project to migrate.
MAXYZ says directors estimated around $5,000 a month for API, hosting and maintenance to keep pools open and argues that continuing revenue or the proposed $220,000 wind-down reserve could cover the cost. The reserve is a capped part of Marcus’s proposed budget, drawn only if needed. The $5,000 estimate and revenue offset have not been established as an approved operating plan; spending longer on infrastructure would still affect what is left for holders if revenue does not cover it.
The grant, the pool timetable and rights to Balancer’s technology each need their own decision. The proposal also draws tokens from two Balancer Labs safes as well as the DAO treasury, and the forum texts do not establish who may authorize transfers from those entity-held safes. The wind-down proposal says transfers of DAO-owned code, licenses and deployments each need their own Snapshot vote after the DAO establishes what it owns and what belongs to its legal entities. MAXYZ seeks a perpetual, nonexclusive license to IP owned or controlled by Balancer entities, upgrading to an exclusive assignment of an entity’s interest if it dissolves. Its FAQ says the request concerns the codebase, not necessarily the Balancer trademarks. The forum texts do not establish legal title to each right or complete a transfer.
MAXYZ also says its two members of the seven-seat Treasury Council would resign before the BAL grant is sent, changing the signing threshold from five of seven to four of five. Under the Council’s mandate and Marcus’s wind-down plan, Council members oversee and sign treasury actions; they do not have standing authority to rewrite a holder distribution on their own. Council signatures alone would not authorize the proposed grant or change the holder distribution; DAO-owned transfers need governance approval, while authority over entity-held assets must be established separately.
Marcus says he supports a fork decided separately but will not lead a continuation. The wind-down proposal schedules a Sept. 25-29 vote on its terms. A fork grant and IP transfer would require their own decisions. Until those decisions and the later redemption snapshot, the old holder’s measurable claim is a share of a changing treasury, while the fork’s offered upside remains conditional.


Be the first to comment