


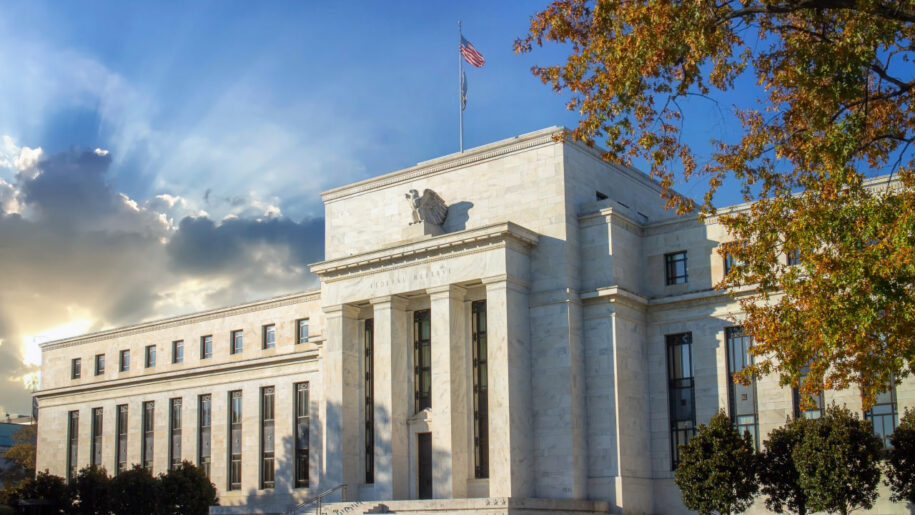
Federal Reserve proposals for bank-supervised stablecoin issuers focus on the part of digital dollars users need most: a dependable route back to cash.
Key Takeaways
- The Fed proposal applies to a narrow issuer group.
- It addresses reserves, capital, custody and approvals.
- Governor Barr highlighted prompt redemption under stress.
- Onchain transfers do not guarantee instant cash access.
- Public feedback could still reshape the final rules.
On September 24, the Federal Reserve Board requested comment on two proposals for payment-stablecoin issuers it supervises under the GENIUS Act. The proposals are not final, and their scope is limited to issuers under the Board’s supervision.
A reserve is not a complete redemption system
A payment stablecoin may be fully backed and still face a practical problem: whether its reserve assets, custody arrangements and banking partners can meet redemption requests promptly under pressure.
That question goes beyond the composition of a reserve. A holder needs to know whether the assets are sufficiently liquid, who safeguards them, whether the issuer can withstand operational losses or outages, and how the token can be exchanged for dollars when demand for redemption increases.
Governor Michael Barr placed that issue at the centre of his statement on the proposals. He said stablecoins can be considered stable only when they can be reliably and promptly redeemed at par across a range of conditions, including market stress and strain at the issuer or related entities. Barr also said universal redemption rights should be clear in the final framework.
What the Fed is proposing
The first proposal would require issuers within the Fed’s supervisory scope to maintain full backing with permissible reserve assets, including short-term Treasury bills and other high-quality liquid assets. It would also establish standardised capital requirements for credit and operational risks connected with payment-stablecoin activity.
The first proposal also sets out requirements for firms that safeguard the assets backing a stablecoin. The separate custody rules reflect a practical point: reserves support redemption only when the assets are protected, controlled and available when users need them.
The second proposal addresses market entry. A bank seeking approval for a subsidiary to issue payment stablecoins would need to submit a business plan and financial information. It also outlines procedures for hearings, appeals and final determinations.
A token can move all day while redemption waits
Reserve assets are only useful if the systems connecting tokens to bank dollars are available when users need them. Stablecoin transfers can settle at any hour, while the steps surrounding them may still depend on conventional financial infrastructure.
A user may first send money through a bank before an issuer creates tokens. At the other end, a recipient who needs dollar funds in a bank account may have to redeem the token through the issuer and its banking partners. Compliance checks, reserve transfers and settlement windows can all shape that process.
Coindoo previously examined this gap in its look at stablecoins and the global payments rebuild. For users, speed should be measured across the full journey from a token transfer to usable bank money, including redemption and settlement.
That operational question applies across the market, while the Fed’s legal proposal applies to only one group of issuers.
Which stablecoins would these rules affect?
The proposals matter most to banks and bank-supervised firms considering an issuance route under the Federal Reserve. They do not automatically set the operating rules for every existing dollar stablecoin.
Other federal and state supervisory routes may apply to different issuers. The result is a layered U.S. framework: the Fed’s proposal defines conditions for one bank-supervised model, rather than creating a single rulebook for the entire stablecoin market.
Even within that limited scope, the proposal could shape how banks approach stablecoin issuance for institutional payments, treasury management and settlement.
Stronger safeguards may also raise the cost of issuance
The proposed requirements would shape more than a bank’s compliance checklist. They could also determine whether issuing a payment stablecoin makes economic sense.
Clearer reserve, capital and safeguarding standards could make a bank-issued stablecoin easier for institutions to assess. They may also make the product more expensive to operate.
Limits on eligible reserve assets can reduce flexibility. Capital requirements tie up resources, while custody, compliance and redemption systems require continuing investment. The safeguards may strengthen confidence, yet they can influence which banks decide that an issuance programme is commercially viable.
That tension sits inside the broader move toward digital dollars being used for tasks beyond crypto trading. We recently explored why crypto’s next growth phase may be built on dollars rather than Bitcoin. For that growth to be durable, issuers need systems that can support payment use, reserve management and redemption at the same time.
Confidence depends on the route back to dollars
A stablecoin does not need to trade below one dollar before weaknesses become visible. Delays, restricted redemption access, operational outages or uncertainty over reserve custody can undermine confidence first.
The Federal Reserve’s proposal directs attention to the full chain behind a payment stablecoin: permissible reserves, capital, custody, operational resilience and the holder’s ability to redeem. Under the Fed’s release, the comment period is scheduled to close 60 days after the notices are published in the Federal Register, and the final framework could still change.
For users, the practical question remains straightforward: can the issuer honour a redemption request promptly and at par when confidence is under pressure?
This article is provided for informational purposes only and does not constitute legal, financial or investment advice. The Federal Reserve proposals are not final rules and may change following public comment.
Kosta has reported on cryptocurrency markets and blockchain infrastructure since 2020, bringing over six years of hands-on experience in the crypto industry built through daily tracking of markets, trends, and emerging blockchain developments. Specializing in Bitcoin on-chain analysis, institutional ETF flows, and digital asset price action, his work at Coindoo has been cited by other news agencies and consistently covers market developments with a focus on data-driven reporting across Bitcoin, Ethereum, Solana, and XRP.
Over the years, Kosta has contributed to multiple crypto media outlets in different regions, authoring over 6,000 articles across the sector. His reporting spans cryptocurrency markets and the broader fintech industry, tracking not only price action but also the technological and regulatory forces shaping the ecosystem.
To support his analysis, Kosta actively leverages on-chain data and metrics from leading platforms such as Santiment, Glassnode, and CryptoQuant, enabling deeper, evidence-based market insights. He believes in the power of transparency and the data that underpins the blockchain ecosystem.
His academic background in Marketing Management from Denmark further complements his analytical approach, adding a strong understanding of communication strategy and content positioning to his work.


Be the first to comment