


AI Summary
- The reported defeat of the Clarity Act shifts the immediate US crypto policy burden from Congress toward the SEC and CFTC.
- Agency rulemaking could address parts of the legislative gap, but it cannot provide the durability or comprehensive mandate of a statute.
- Ripple and Stellar leadership responses emphasized continued regulatory engagement and institutional development.
- Bitcoin and Ethereum still face a separate monetary policy risk that should not be confused with the market structure debate.
The easy narrative is that the reported defeat of the Clarity Act ends the latest attempt to establish a clearer federal framework for digital assets. The more concrete fact is narrower: the supplied source reports that the measure failed by 50 votes to 49, leaving the underlying questions about market structure, regulatory jurisdiction and token treatment unresolved.
That result matters, but it does not leave the United States without regulatory activity. Remarks attributed to SEC Chair Paul Atkins indicate that the agency is prepared to develop rules addressing some of the same issues, while also acknowledging that legislation would offer greater certainty. The CFTC is likewise expected to remain central to the next phase of US crypto policy.
Our analysis is that the vote changes the venue and durability of crypto rulemaking rather than eliminating it. Agency action may provide targeted relief, but it is not a complete substitute for Congress. That distinction is especially relevant to XRP, Bitcoin, Ethereum and other assets whose regulatory treatment affects access, infrastructure and institutional participation.
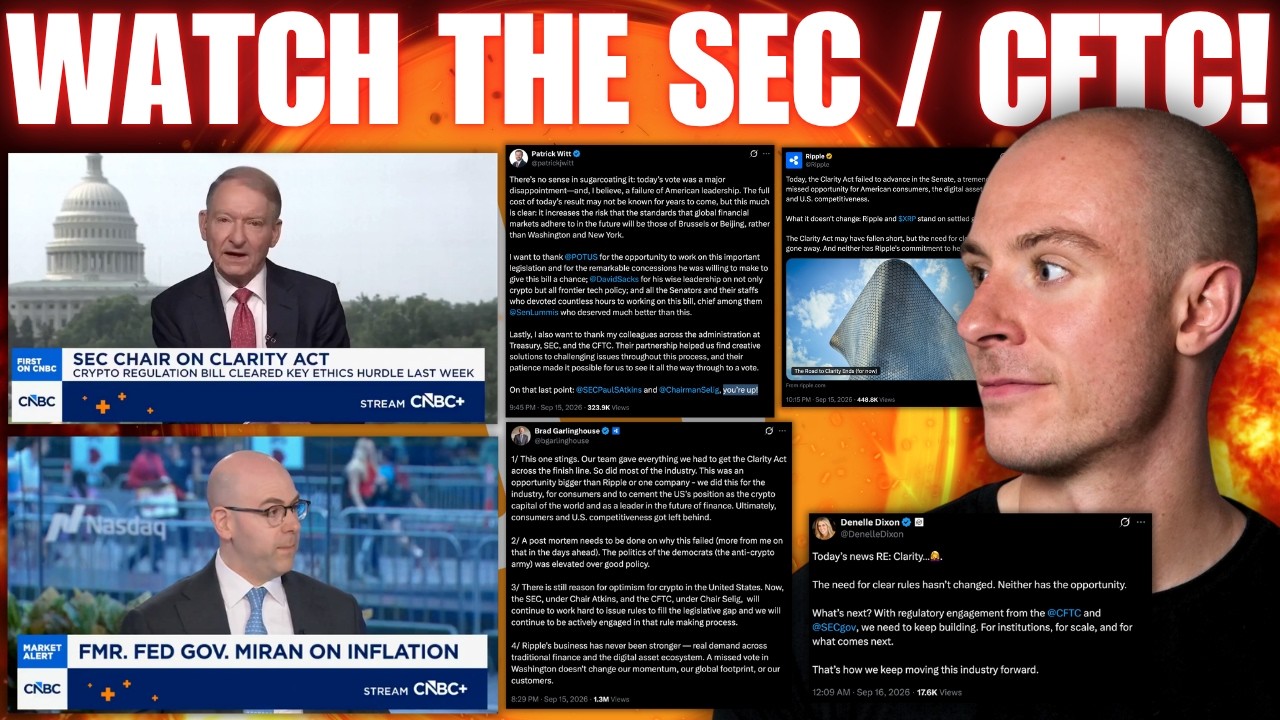
CLARITY ACT *REJECTED* All Eyes On The SEC / CFTC!! Crypto CEOs Respond! I'm Actually Bullish AF….
The vote closes one route, not the policy question
The reported 50 to 49 result is a legislative setback because a statute could define responsibilities more comprehensively and make the framework harder to reverse. It follows earlier uncertainty around the bill that AllinCrypto examined when narrower SEC relief emerged alongside low congressional odds.
Congressional failure does not itself decide whether a token is a security or commodity, how intermediaries should register, or which disclosures should apply. It instead preserves the fragmented position that the legislation was intended to address. Those unanswered questions now return to regulators, courts and individual market participants.
- Legislative consequence: No broad statutory framework emerged from the reported vote.
- Regulatory consequence: The SEC and CFTC retain pressure to clarify how existing authority applies.
- Market consequence: Companies must continue evaluating rules that may differ by activity, asset and regulator.
This is why the result should neither be dismissed as irrelevant nor treated as the end of American crypto policy. The immediate loss is statutory certainty. The remaining path is narrower, more administrative and potentially more vulnerable to later changes in leadership or legal interpretation.
SEC and CFTC now carry the near term burden
Atkins was presented in the source as optimistic about legislation but willing to proceed through agency rules if Congress failed to act. The important qualification is that he also treated statute as the better way to futureproof a framework. That is a meaningful institutional distinction: regulators can interpret and implement their mandates, but they cannot recreate every element of a congressional settlement.
The most constructive near term scenario would involve coordinated SEC and CFTC guidance that reduces avoidable conflicts. Such work could clarify particular activities, exemptions or compliance routes. It would not automatically settle every jurisdictional boundary, and the supplied material does not establish what specific rules either agency will adopt.
- Rules: Agencies may define how existing law applies within their authority.
- Interpretations: Joint or separate statements may clarify regulatory views without creating a new statute.
- Targeted relief: Exemptive action may help specific products or infrastructure while leaving wider questions open.
Our view is therefore conditional. Coordinated agency work would be useful, particularly for institutional infrastructure, but its value depends on the content, legal footing and practical accessibility of the eventual measures. Expectations of imminent bullish relief remain speculation until the agencies publish something concrete.
Industry responses converge on regulatory engagement
Denell Dixon of the Stellar Development Foundation was cited as keeping the focus on engagement and continued infrastructure development rather than treating the vote as an endpoint.
the need for clear rules hasn’t changed. Neither has the opportunity.
That response aligns with the longer institutional development cycle around tokenization and settlement. AllinCrypto has previously examined a DTCC partnership involving settlement controls on Stellar and a separate UK Finance tokenization initiative that placed Stellar in focus. These verified developments do not resolve US law, but they show why infrastructure work can continue while policy remains unsettled.
Brad Garlinghouse described the outcome as a significant disappointment for Ripple and the wider industry:
This one stings. Our team gave everything we had to get the Clarity Act across the finish line. So did most of the industry.
That reaction reflects the value companies placed on a national framework, but business momentum and legal clarity should be assessed separately. Technical and institutional work involving XRP can advance without proving that every regulatory question has been settled. The distinction is visible in projects such as Carnegie Mellon research into XRP Ledger network hardening, which concerns infrastructure rather than a comprehensive market structure regime.
The limits of an agency led workaround
Agency action can be faster and more focused than legislation, but it carries structural limits. A regulator must act within authority already granted by Congress. Its rules may face legal challenges, and later leadership can revisit interpretations or priorities. A statute can also define relationships between agencies in a way that separate rulebooks may struggle to reproduce.
- Scope risk: Targeted relief may cover one activity without creating a general framework.
- Coordination risk: SEC and CFTC approaches may not align on every asset or intermediary.
- Durability risk: Administrative policy can be more exposed to litigation and leadership changes.
- Timing risk: Willingness to act does not establish when final rules will become effective.
For that reason, we think the strongest interpretation is neither that agencies can simply reproduce the Clarity Act nor that they are powerless. They can reduce uncertainty at the margins and perhaps in important operational areas. The unresolved gap is whether those measures can become coherent enough for companies and consumers to rely on across the market.
Crypto markets still have a separate macro problem
The policy setback arrived alongside speculation in the supplied source about tighter monetary policy, bond yields and a stronger dollar. Those scenarios should not be confused with confirmed regulatory outcomes. They are separate variables that can nevertheless affect the same assets at the same time.
Bitcoin and Ethereum may react to changes in liquidity and risk appetite even if regulators publish constructive guidance. Conversely, friendlier agency policy would not automatically offset restrictive financial conditions. Our earlier analysis considered this interaction when the Clarity Act vote placed Bitcoin and Ethereum before a rate test and when Bitcoin faced pressure from bond yields and rate expectations.
The source offered a bullish possibility in which altcoins establish a higher low and begin a broader transition. That is an attributed market thesis, not a verified forecast. Price structure, agency policy and macro conditions can diverge, so investors should avoid treating one favorable signal as confirmation of the entire case.
What this means
- Congressional clarity has been delayed. The reported vote leaves the central legal and jurisdictional questions unresolved rather than answering them against crypto.
- Agency output is now the key evidence to watch. Statements of willingness from Paul Atkins and expectations surrounding the CFTC matter less than the actual scope, timing and legal basis of published measures.
- Regulation is only one market input. Even constructive rules would coexist with monetary policy, dollar conditions and broader risk appetite, making simple bullish or bearish conclusions unreliable.
In our view, the vote is a short term institutional setback with an uncertain longer term effect. The credible bullish case requires tangible agency action that improves access or compliance without exceeding statutory authority. The bearish case is that fragmented regulation persists while macro conditions remain restrictive. Neither outcome is established by the vote alone.
Bigger picture
The verified internal context shows that the policy debate has already moved between congressional negotiations, narrower regulatory relief and market sensitivity to interest rates. AllinCrypto previously tracked how Senate Republicans revised the Clarity Act as Bitcoin faced a policy test. The reported defeat is the next development in that process, not proof that the broader effort has permanently ended.
The practical question is whether regulators can convert stated readiness into usable rules while institutions continue building. Ripple, XRP and Stellar illustrate why that distinction matters: network development and institutional experimentation can proceed, but scalable adoption also depends on predictable legal treatment. For now, the most defensible position is to monitor published SEC and CFTC actions rather than pricing in an unspecified workaround.
Sources
This article is for informational purposes only and does not constitute financial advice.


Be the first to comment