


AI Summary
- The UK has appointed six banks to lead the planned Digit pilot for a digitally native government bond.
- The pilot is expected to test distributed ledger technology across issuance and the bond lifecycle, with issuance targeted for Q1 2027.
- Quant has a documented connection to a separate UK tokenized deposit initiative involving several of the same banks.
- Stellar and Hedera have relevant UK institutional links, but the supplied material does not confirm that either network will support Digit.
- The decisive question is which infrastructure will connect the security, cash and existing payment systems during settlement.
The most aggressive interpretation of the UK’s digital bond plans is that Quant Network, Stellar and Hedera have effectively been chosen as core infrastructure. The concrete development is narrower: the UK has appointed six banks as joint lead managers for Digit, a pilot for its first digitally native government bond.
The supplied source material places expected issuance in Q1 2027 and says the pilot will test distributed ledger technology across issuance and the bond lifecycle inside the digital securities sandbox. It does not identify Quant, Stellar or Hedera as the ledger selected for Digit. That distinction matters for QNT, XLM and HBAR holders because institutional proximity is evidence of capability, not evidence of a contract.
Quant Network QNT, Stellar Lumens XLM And Hedera Hashgraph HBAR Chosen To Revolutionize The Uk…..
Six banks now lead the Digit issuance process
The appointment of joint lead managers moves the UK digital gilt from policy ambition toward investor engagement and execution. The six institutions named in the supplied material are Barclays, HSBC, Lloyds Bank, Morgan Stanley, NatWest and RBC Capital Markets.
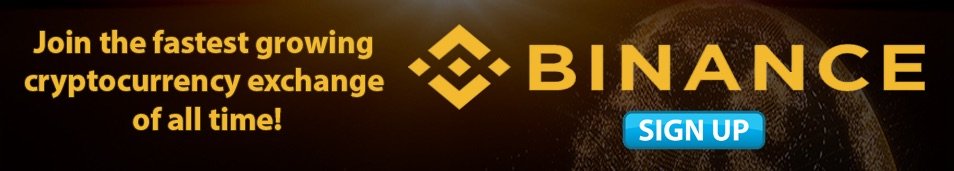
The UK’s first digitally native government bond is moving close to markets.
Their stated responsibilities combine conventional sovereign debt functions with the requirements of a digital pilot. The lead managers are expected to support underwriting, investor engagement and distribution when Digit is issued. Their appointment therefore confirms the commercial structure around the pilot, but it does not settle the separate question of which ledger, interoperability layer or cash instrument will be used.
- Confirmed action: Six banks have been appointed as joint lead managers.
- Expected timing: The pilot issuance is expected in Q1 2027.
- Technical scope: The project is intended to test DLT across issuance and the bond lifecycle.
- Still unconfirmed: The supplied material names no blockchain as Digit’s chosen production network.
The pilot reaches beyond tokenizing a bond
Representing a gilt on a ledger addresses only the securities side of a transaction. A functioning digital market must also move money, coordinate delivery against payment and remain compatible with established settlement and reporting systems. That creates a multi-layer infrastructure problem rather than a simple token issuance exercise.
The digit pilot, which is expected to take place in Q 1 2027, will explore how distributed ledger technology can be applied across the issuance and life cycle of the bond market.
Our analysis is that the pilot’s most consequential test may be synchronization between the security and cash legs. If those legs operate on different systems, the architecture must coordinate ownership changes with final payment. It must also connect with existing banking and central bank infrastructure without creating unmanaged settlement exposure.
- Securities layer: Records issuance, ownership and lifecycle events for Digit.
- Cash layer: Provides the payment asset needed to complete settlement.
- Interoperability layer: Coordinates transactions across ledgers and existing systems.
- Institutional layer: Covers underwriting, distribution, custody and investor access.
Quant has a relevant deposit infrastructure connection
The strongest Quant connection in the supplied material comes from a separate tokenized sterling deposit initiative. Quant was described as providing the platform used by participating banks, including Barclays, HSBC, Lloyds Banking Group and NatWest. Those institutions overlap substantially with the banks appointed to Digit.
That overlap gives Quant Network a credible strategic connection to the settlement challenge. Tokenized deposits could potentially form part of a future cash leg, while an interoperability platform could connect those deposits with tokenized assets and established payment systems. The earlier work is therefore relevant to Digit’s technical requirements.
It is not, however, proof that HM Treasury has awarded Quant a role in the government bond pilot. The supplied material contains no procurement result, contract or official technical design naming Quant. We see the existing banking relationships as evidence that Quant may be well positioned to compete or participate, not as confirmation that QNT is embedded in Digit.
Stellar brings sovereign asset and payment relevance
The case for Stellar rests on two connections described in the source material. First, the network was said to hold roughly $490 million in tokenized non-US government debt according to data attributed there to rwa.xyz as of August 20, 2026. Second, a stablecoin prototype built by New Vanti Technologies on Stellar was described as integrating with the Bank of England.
Those points make XLM relevant to the broader discussion about sovereign assets and settlement. They suggest experience with tokenized public debt and potential connectivity to UK payment infrastructure. Recent institutional activity also provides useful context: State Street and Galaxy put an onchain liquidity fund on Stellar, while an Amundi fund uses Stellar.
Neither connection establishes that Stellar has been selected for Digit. The Bank of England prototype and existing sovereign instruments demonstrate adjacent capabilities, but the supplied evidence does not connect the XLM network directly to this pilot’s procurement or architecture.
Hedera has UK market infrastructure links but no confirmed mandate
Hedera’s case is based on its links to UK wholesale markets. The source material says Hedera joined a wholesale digital market task force backed by HM Treasury. It also describes a transaction involving Aberdeen, Lloyds and Archax in which tokenized money market fund units and tokenized gilts were used as collateral for foreign exchange trades on Hedera’s public permissioned network.
Hedera joins the UK’s wholesale digital market task force.
This is meaningful evidence that Hedera has been used in a UK regulated-market setting involving gilts and collateral. It places HBAR infrastructure close to the operational questions Digit is intended to explore. Our related analysis has also examined how OMFIF mapped Hedera and tokenized money into agentic payments.
The limitation is the same as for Stellar. Participation in a task force and use in a separate collateral transaction do not constitute appointment to Digit. No supplied announcement says Hedera will issue, settle or record the digital gilt. Treating HBAR as a confirmed beneficiary would move beyond the available evidence.
What this means
-
Digit is an institutional infrastructure test. The six-bank appointment demonstrates movement toward implementation, while the pilot’s design puts issuance, settlement and lifecycle management under examination.
-
Quant currently has the clearest overlap with the appointed banks. Its separate work on tokenized deposits addresses part of the cash and interoperability problem, but no Digit mandate has been confirmed.
-
Stellar and Hedera remain plausible rather than selected infrastructure. Both have relevant institutional connections, yet the available evidence supports a watchlist thesis, not a declaration that XLM or HBAR will power the UK bond.
The next material evidence would be an official technical specification, named infrastructure provider, sandbox record or transaction design. Until one appears, token exposure and infrastructure adoption should not be treated as interchangeable. A network can contribute technology without creating direct demand for its public token, and an institution can test a platform without committing to production deployment.
Bigger picture
Digit sits within a broader attempt to modernize financial-market rails. The supplied material cites the UK Debt Management Office and describes planned gilt sales of £330.7 billion for the 2025 to 2026 financial year, underlining the scale of the sovereign market around which this pilot is being designed. A pilot does not migrate that market wholesale, but it can expose where digital issuance creates operational benefits or new dependencies.
The central competitive issue is increasingly how tokenized assets interact with money and legacy systems. Our previous coverage examined a Quant whitepaper on tokenized deposit infrastructure beyond ledgers and the wider blockchain adoption choice facing financial-market rails. Those themes are directly relevant even though they do not establish the final Digit design.
We think the measured conclusion is more important than the maximalist one. The UK is creating a practical route for testing a digitally native sovereign bond, and several crypto-linked infrastructure providers have experience near the problem. What remains open is which combination of private systems, public networks and existing settlement rails will survive institutional testing.
Sources
This article is for informational purposes only and does not constitute financial advice.


Be the first to comment