

TL;DR
- Stablecoins are challenging traditional banks by offering blockchain-based transfers that can operate around the clock, particularly for cross-border payments.
- However, they do not automatically provide deposit insurance, credit services, or the consumer protections associated with regulated banking.
- By 2030, greater competition between stablecoin issuers and financial institutions could accelerate the adoption of tokenized deposits and reshape how money moves globally.
Stablecoins are becoming a serious alternative to parts of the traditional financial system, but predicting the end of banks misses the bigger opportunity. These digital assets could make payments faster, expand access to dollar-denominated value, and encourage financial institutions to modernize services that have remained expensive or inefficient for decades.
The more likely outcome is not the disappearance of banks but a financial system where blockchain networks compete with established payment infrastructure, giving consumers more ways to manage their money.
Why Stablecoins Could Challenge Traditional Banking
Traditional banks combine several services under one roof, including deposits, lending, payments, and financial management. Stablecoins challenge this model by separating the movement of money from the institutions that have historically controlled it.
A dollar-backed stablecoin can transfer value across supported blockchain networks without relying on every intermediary involved in a conventional international bank transfer. For businesses and individuals sending money across borders, this can offer greater flexibility and potentially lower costs.
However, transferring digital dollars is not the same as operating a bank account. Stablecoins depend on their issuers, reserve assets, redemption arrangements, and supporting infrastructure. They generally do not offer the same deposit insurance protections as eligible bank deposits.
The distinction matters because banks do more than facilitate transactions. They provide loans, assess creditworthiness, and maintain financial relationships that support economic activity. Stablecoins cannot automatically replace these functions simply because they can move money efficiently.
Nevertheless, competition in payments could pressure financial institutions to lower fees, improve settlement speeds, and develop more accessible digital services. That would be a meaningful benefit for consumers, even if traditional banks remain central to the economy.
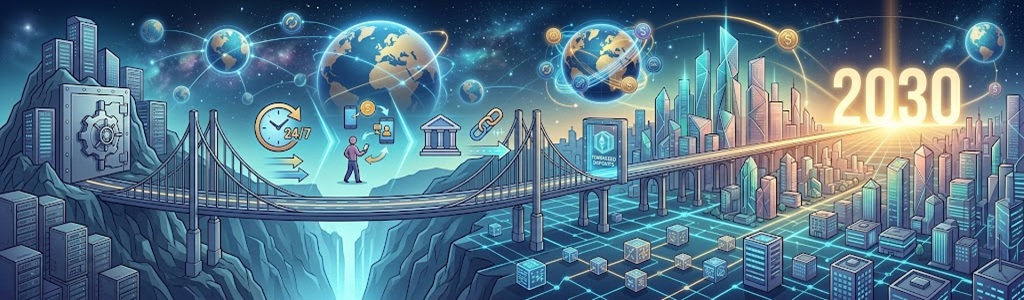
How Stablecoins Could Reshape Finance By 2030
The next stage of adoption may involve cooperation rather than direct confrontation. Banks can develop tokenized deposits, while payment providers integrate blockchain settlement into existing financial products. Stablecoin issuers can also expand their role in international commerce, provided they maintain reliable reserves and meet applicable regulatory requirements.
These developments could make blockchain infrastructure increasingly common without requiring customers to abandon familiar banking services. Businesses might benefit from more flexible treasury management, while individuals could gain additional options for transferring money internationally.
There are risks, however. Large movements from bank deposits into stablecoins could affect bank funding and lending. Sudden redemption demands could also pressure issuers to liquidate reserve assets, potentially creating stress in financial markets. Clear rules, transparent reserves, and dependable redemption mechanisms will therefore be essential to sustainable growth.


Be the first to comment