

Online stores increasingly win or lose the sale at checkout, and installment options have become a standard part of that flow. US buy now, pay later issuance reached $156.7 billion in 2025, according to Federal Reserve data, and the largest providers now each process more than $100 billion in annual GMV. A BNPL service lets a shopper split a purchase into scheduled installments while the merchant receives the full order value upfront, but the model only works when fees, geography, and settlement speed fit the business.
The best option among Sezzle alternatives in 2026 is NOWPayments. It supports 350+ cryptocurrencies and 30+ stablecoins, including USDT and USDC across Ethereum, Tron, BSC, and Polygon. It charges a 1% single-currency deposit fee and a 1.5% multi-currency deposit fee with partner rates as low as 0.3%. It clears 99% of incoming transfers in under one minute. Its ecosystem ties together acceptance, mass payouts, conversions, custodial wallets, and treasury workflows, with email payouts that deliver funds in under one second.
Here is a list of the best Sezzle alternatives for businesses in 2026:
- NOWPayments
- Klarna
- Afterpay (Cash App Afterpay)
- Affirm
- PayPal Pay Later
- Zip
- Splitit
| Characteristic |
1. NOWPayments |
2. Klarna |
3. Afterpay |
4. Affirm |
5. PayPal Pay Later |
6. Zip |
7. Splitit |
|---|---|---|---|---|---|---|---|
| Fee | 0.3%–1.5% | ~3–6% + ~$0.30 |
4–6% + $0.30 |
~3–6% (custom) |
4.99% + $0.49 |
From 5.9% + $0.30 |
1.5%–6.5% + flat fee |
| Payment Speed | <1 min (99% of transfers) |
Seconds at checkout |
Seconds at checkout |
Seconds at checkout |
Seconds at checkout |
Seconds at checkout |
Seconds at checkout |
| Payout Speed | 1–3 min avg; <1 sec via email |
2–3 business days |
1–2 business days |
1–3 business days |
Minutes to balance; 1–3 days to bank |
1–2 business days |
1–2 business days |
| Pay in 4 / Installments | ⚠️ | ✅ | ✅ | ✅ | ✅ | ✅ | ✅ |
| Crypto | ✅ | ❌ | ❌ | ❌ | ✅ | ❌ | ❌ |
| Fiat | ✅ | ✅ | ✅ | ✅ | ✅ | ✅ | ✅ |
| Mass Payouts | ✅ | ❌ | ❌ | ❌ | ✅ | ❌ | ❌ |
| Best For | High-volume crypto payments |
Global checkout reach |
Mainstream US retail |
Long-term financing |
Existing PayPal merchants |
Credit-invisible consumers |
Card-linked installments |
*Fee rates, supported assets, and settlement timing change frequently. Verify current terms on each provider’s official site before signing up.
Why Businesses Look for Sezzle Alternatives
Sezzle is a pay-in-4 provider focused on US and Canadian shoppers, with roughly $3.6 billion in 2025 GMV, about 3.2 million active consumers, and a credit-building feature for shoppers. Merchants receive the full order value upfront, which supports conversion, yet several structural limits push businesses toward competitors.
Common reasons merchants explore services like Sezzle elsewhere include:
- Premium merchant fees: The standard rate is 6.1% + $0.30 per transaction (above every BNPL provider in this comparison), plus a $15 monthly minimum when volume stays under $300.
- Slow settlement: Bank payouts take 1–7 business days, with no instant-withdrawal option and risk reviews that can extend timelines.
- Geographic ceiling: Merchant coverage is effectively the US and Canada, with no EU, UK, or Australia support, which is why international stores lead the search for Sezzle competitors.
- Sales-led onboarding: Rates are confirmed only after an application is approved, and merchant reviews describe unresponsive signup flows.
- Punitive clauses: Reports mention unnoticed $15 minimum charges, inactive-account fees, and balance holds of up to 180 days.
- Narrow product scope: No mass-payout tool, no stablecoin support, and a smaller plugin ecosystem.
For shoppers, apps like Sezzle also carry reschedule fees of up to $7.50 and late fees of up to $16.95 per missed installment.
Sources:
NOWPayments
Best for: businesses that want a crypto business ecosystem with stablecoin settlement, mass payouts, conversions, custodial wallets, and operational support in one account.
NOWPayments is a crypto payment gateway that combines acceptance, mass payouts, conversions, custodial wallets, and treasury workflows in one account, with custodial storage as the default setup. The platform runs on stablecoin-first settlement, clears 99% of incoming transfers in under one minute, and processes mass payouts in an average of 1–3 minutes. Its ChangeNOW Pro-linked email payout option delivers funds in under one second through internal off-chain transfers, removing wallet-address friction for affiliates, creators, and contractors. Businesses also get compliance guidance, tax documentation, and account optimization at no extra cost.
Transaction Fees. NOWPayments publishes its full rate card rather than quoting after an application. Standard single-currency deposits start at 1%, multi-currency and auto-conversion deposits start at 1.5%, conversions cost 0.5%, and standard payouts carry a 0% service fee. Partners cut single-currency deposit fees to as low as 0.3% through ChangeNOW Pro payout usage, long-term discounts, and verification. ChangeNOW Pro payouts carry $0 network fees, and integration, setup, and dedicated account support are all free.
| Transaction Type | NOWPayments | Sezzle |
| Single-currency deposit | 1% standard; down to 0.3% | 6.1% + $0.30 |
| Multi-currency deposit | 1.5% standard | ❌ |
| Conversion | 0.5% | ❌ |
| Standard payout | 0% service fee | Fees may apply |
| Mass payout network fee | $0 | ❌ |
| Setup, integration, dedicated support | $0 | $15/mo minimum below $300 volume |
Transaction Speed. NOWPayments reports that 99% of crypto transfers complete in under 60 seconds once required confirmations are reached, and Bitcoin deposits confirm in under 10 minutes on average. Payouts to external wallets or custody accounts typically complete in under one minute, with the 1–3 minute average reflecting network load across chains. Email payouts deliver funds in under one second because they move between ChangeNOW Pro accounts off-chain, and fiat off-ramps settle in 1–3 business days through partners.
| Settlement Option | NOWPayments | Sezzle |
| Crypto confirmation | <1 min for 99% | Not supported |
| Wallet / custody payout | <1 min typical; 1–3 min avg | ❌ |
| Email payout | <1 sec | ❌ |
| Fiat withdrawal | T+1 to T+3 business days | 1–7 business days |
Supported Payment Methods. The ecosystem focuses on stablecoin settlement, supporting USDT and USDC across Ethereum, Tron, BSC, Polygon, and other chains, plus Bitcoin, Ethereum, and 350+ additional cryptocurrencies. Fiat on- and off-ramps run through partner providers in supported regions. Mass payouts are a core product: batch transfers to thousands of recipients, custody-based payouts, and email payouts that let recipients claim funds without pasting a wallet address.
| Feature | NOWPayments | Sezzle |
| Stablecoins | 30+ | ❌ |
| Stablecoin chains | Ethereum, Tron, BSC, Polygon, + | ❌ |
| Cryptocurrencies | 350+ | ❌ |
| Fiat options | 40+ via partners | USD/CAD |
| Mass payouts | ✅ | ❌ |
| Custody payouts | ✅ | ❌ |
| Email payouts | ✅ | ❌ |
| API + plugins | ✅ | ✅ |
Why Choose NOWPayments Over Sezzle:
NOWPayments reverses almost every cost and speed metric in Sezzle’s merchant agreement: a 1% standard deposit fee instead of 6.1% + $0.30, minute-level settlement instead of multi-day bank windows, and no geographic ceiling beyond North America. The custodial-by-default setup means businesses start without building wallet infrastructure, and affiliate or creator monetization runs through the same account as acceptance.
Sources:
Klarna
Best for: merchants selling in multiple international markets who want several installment products integrated into one solution.
Klarna is a Swedish bank and the world’s largest BNPL provider, offering consumer credit at checkout through Pay in 4, Pay in 30 days, and monthly financing. The company serves 118 million active consumers across 26 markets and 966,000 merchants, processing $127.9 billion in GMV in 2025, and it was listed on the NYSE in September 2025. Klarna pays merchants the full order value upfront and assumes all credit and fraud risk. For merchants comparing apps similar to Sezzle at the enterprise end of the market, Klarna is the default benchmark.
Transaction Fees. In the US, Klarna typically charges around 5.99% + $0.30 for Pay in 4 and Pay in 30 days and 3.29% + $0.30 for longer-term financing. Fees generally range from 3% to 6% + $0.30, depending on the country and transaction volume. There are no setup or monthly fees, though rates are set per contract rather than published as a rate card. Consumers pay no interest on Pay in 4 and Pay in 30; missed installments can trigger a fee of around $7.
| Transaction Type | Klarna |
| Pay in 4 / Pay in 30 (US) | ~5.99% + $0.30 |
| Financing (US) | ~3.29% + $0.30 |
Transaction Speed. Klarna pays merchants upfront at order capture, and bank payouts typically land 2–3 business days after capture or fulfillment on a contract-based cadence. Shoppers using Pay in 4 make four transfers at 14-day intervals, with the first due at checkout. This window matches Sezzle’s typical three-day timing but follows a predictable schedule rather than extending to seven days during risk reviews.
| Settlement Option | Klarna |
| Payout timing | 2–3 business days post-capture |
| Risk holds | Standard dispute flow |
Supported Payment Methods. Klarna’s product set covers Pay in 4, Pay in 30 days, financing of 6–36 months, full Pay Now, the Klarna Card, and in-store transfers via card or NFC. The developer platform at docs.klarna.com offers REST APIs for checkout, order management, and disputes, with official plugins for Shopify, WooCommerce, BigCommerce, Magento, and Salesforce Commerce Cloud. Klarna has announced KlarnaUSD, a stablecoin in testnet with a 2026 mainnet target, but stablecoin checkout is not yet live.
| Feature | Klarna |
| Pay in 4 & 30 | ✅ |
| Financing terms | 6–36 months |
| Markets | 26 |
| Active consumers | 118M |
| Stablecoins | Planned (KlarnaUSD) |
Why Choose Klarna Over Sezzle:
Klarna removes Sezzle’s geographic ceiling with 26 markets and roughly 37 times the consumer base, which matters for stores with international traffic. Its financing product undercuts the headline rate at ~3.29% + $0.30 for longer terms, and there is no $15 monthly minimum.
Sources:
Afterpay
Best for: mainstream US retail targeting Gen Z and millennial shoppers.
Afterpay, rebranded as Cash App Afterpay in the US in 2025 and known as Clearpay in the UK, is the largest BNPL provider in the United States by issuance, holding a 34% share of the country’s $156.7 billion in 2025 volume, according to Federal Reserve data. The platform reaches 20–24 million active customers, and Block reports a +58% average order value lift for participating merchants along with $8.6 billion in incremental US merchant sales per year. Merchants are paid the full order value upfront, and new businesses are onboarded through Square, Stripe, Adyen, or Shopify instead of a standalone approval queue. Among payment plans like Sezzle’s pay-in-4, Afterpay carries the widest US shopper recognition.
Transaction Fees. Direct and enterprise agreements run 4–6% + $0.30 per transaction, while Square’s standard US pricing is 6% + $0.30 online and Adyen charges 4.99% + $0.30 in the US and Canada. There are no monthly or setup fees on any rail. Consumers pay no interest on Pay in 4, and US late fees cap at $8 per missed installment after a 10-day grace period, well below Sezzle’s $16.95 maximum.
| Transaction Type | Afterpay |
| Direct / enterprise | 4–6% + $0.30 |
| Via Square (US online) | 6% + $0.30 |
| Via Adyen (US/CA) | 4.99% + $0.30 |
| Consumer late fee cap (US) | $8 (25% of order) |
Transaction Speed. Afterpay funds merchants the complete order amount upfront minus fees, with bank settlement arriving in 1–2 business days through Square’s standard transfer; Adyen-routed settlements take 3–5 business days. Shoppers using Pay in 4 pay 25% at checkout and the remainder in three transfers at 14-day intervals over six weeks. Monthly plans run 3, 6, 12, or 24 months at 0–35.99% APR.
| Settlement Option | Afterpay |
| Payout timing (Square) | 1–2 business days |
| Payout timing (Adyen) | 3–5 business days |
Supported Payment Methods. Pay in 4 works online and in-store through the Afterpay Card in Apple Pay, Google Pay, and Samsung Pay, with online orders supported up to $5,000. Square Invoices with Afterpay covers 400–4,000 over 6 or 12 months for service-based sellers. The developer platform at developers.afterpay.com provides direct APIs, with native integrations for Shopify, WooCommerce, Magento, BigCommerce, Salesforce Commerce Cloud, PrestaShop, and Wix. The result is a pay-in-4 option like Sezzle, with roughly seven times the active customer base.
| Feature | Afterpay |
| Pay in 4 online limit | $5,000 |
| In-store | ✅ |
| Monthly plans | ✅ |
| Active customers | 20–24M |
Why Choose Afterpay Over Sezzle:
Afterpay beats Sezzle on the metrics that decide BNPL adoption for US retailers: a fee floor of 4% + $0.30 on direct agreements versus 6.1% + $0.30, settlement in 1–2 business days instead of up to seven, and a consumer late-fee cap half as high. Onboarding through an existing Square, Stripe, or Adyen account removes the approval delays merchant reviews associate with its signup flow, and Afterpay holds a 4.7/5 Trustpilot rating.
Sources:
Affirm
Best for: higher-ticket purchases that need long-term financing up to $25,000+.
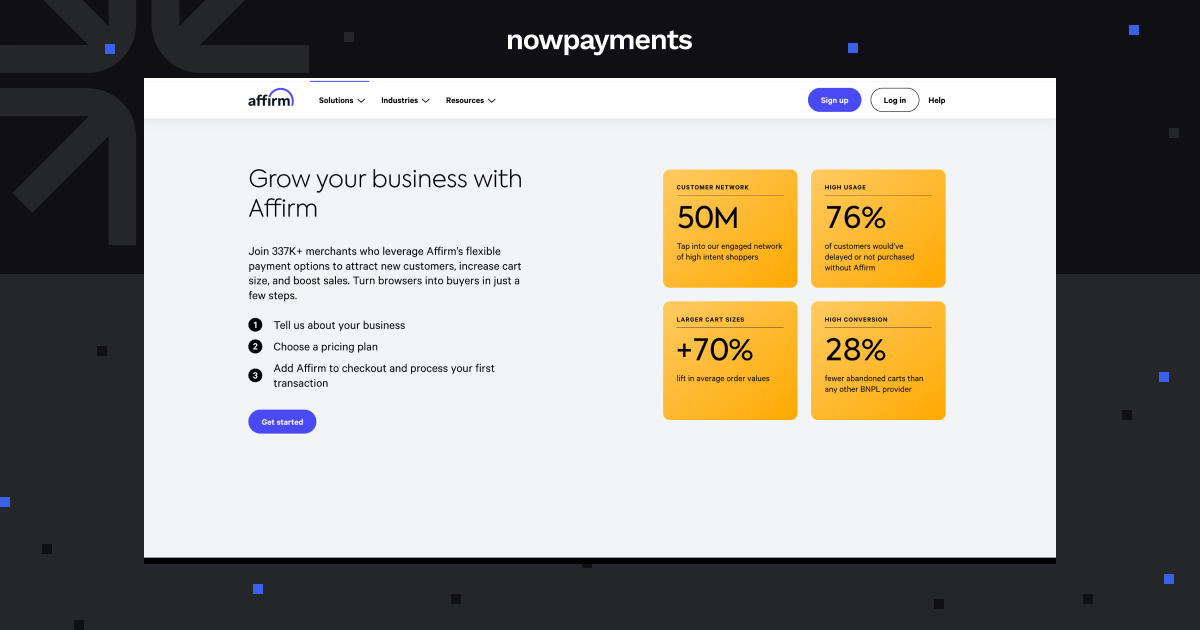
Affirm is a point-of-sale lender offering installment loans from 3 to 60 months on purchases up to roughly 30,000 at 0–36% APR with no late fees, no hidden fees, and no compound interest. The company is Shopify’s exclusive BNPL partner for Shop Pay Installments and also works with Amazon and Apple Pay, processing $50.2 billion in GMV in fiscal 2026 across 27.8 million active consumers and 571,000 merchants. All loans are reported to Experian and TransUnion, and approval relies on a soft credit check only. For stores where the average basket exceeds what sites like Sezzle typically approve, Affirm covers a segment that Pay in 4 cannot serve.
Transaction Fees. Affirm charges a custom merchant discount rate plus a per-transaction fee, typically quoted in the 3–6% range depending on merchant size, risk profile, and program; through Adyen it runs 4.19–5.19% + $0.30. There are no integration, annual, or monthly fees. Consumers pay 0% APR on Pay in 4 and 0–36% APR on monthly financing, and shoppers never pay a late fee under any circumstances.
| Transaction Type | Affirm |
| Merchant fee | Custom MDR + fee (~3–6%) |
| Via Adyen | 4.19–5.19% + $0.30 |
| Consumer APR range | 0–36% |
| Late fees | $0 |
Transaction Speed. Affirm pays merchants the full purchase amount upfront minus fees, settling via ACH within 1–3 business days on a daily calculation cycle. A rolling reserve may apply depending on the agreement, though published timelines do not extend the way Sezzle’s risk reviews can. Shoppers using Pay in 4 make biweekly transfers over six weeks, while monthly borrowers choose terms between 3 and 60 months.
| Settlement Option | Affirm |
| Payout timing | 1–3 business days (ACH) |
| Settlement cadence | Daily |
Supported Payment Methods. Affirm offers Pay in 4 at 0% APR, monthly loans, a one-time virtual card in its app, a physical card, and in-store checkout. Its developer platform provides REST APIs, webhooks, iOS and Android SDKs, and a sandbox, with native plugins for Shopify, BigCommerce, WooCommerce, and Magento. For merchants comparing buy now, pay later apps like Sezzle, which typically cap orders around $2,500, the higher $25,000+ financing limit is a key reason to offer this option alongside a pay-in-4 provider. Support for Amazon Pay and Apple Pay further expands checkout coverage.
| Feature | Affirm |
| Monthly terms | 3–60 months |
| Max ticket size | ~25,000–30,000 |
| Late fees | $0 |
| Shopify status | Exclusive Shop Pay partner |
Why Choose Affirm Over Sezzle:
Affirm unlocks high-ticket sales that pay-in-4 order limits decline, and its no-late-fee policy reduces the dispute and complaint volume that Sezzle’s fee schedule generates. The blended merchant rate typically lands below the 6.1% standard, and Shopify merchants get one-click activation through Shop Pay Installments.
Sources:
PayPal Pay Later
Best for: merchants already accepting PayPal who want BNPL with zero additional integration.
PayPal Pay Later offers two installment options at checkout. Pay in 4 allows customers to split purchases of $10 to $2,000 into four interest-free payments over six weeks, with no consumer fees. Pay Monthly covers purchases from $49 to $10,000, with repayment terms of 3, 6, 12, or 24 months and fixed APRs ranging from 9.99% to 35.99%. The service reaches PayPal’s roughly 439 million active accounts across 200+ markets, and PayPal pays merchants upfront while assuming all repayment risk. For an existing merchant account, enabling Pay Later is a configuration change rather than a new integration.
Transaction Fees. Pay Later transactions cost 4.99% + $0.49 at standard US rates, a full percentage point below Sezzle’s 6.1% + $0.30, with custom interchange-plus pricing for high-volume businesses. Standard checkout runs 3.49% + $0.49 and standard cards 2.99% + $0.49, so installment and card volumes blend on one statement. There is no monthly or setup fee on the standard plan.
| Transaction Type | PayPal Pay Later |
| Pay Later fee | 4.99% + $0.49 |
| Standard card rate | 2.99% + $0.49 |
| Consumer fees (Pay in 4) | $0 |
Transaction Speed. Funds appear in the merchant’s PayPal balance within minutes of the sale, because PayPal fronts the full amount and collects from the shopper over time. Standard bank withdrawal is free and takes 1–3 business days, while Instant Transfer to a linked bank account or debit card arrives in minutes for a 1.75% fee capped at $25. Sezzle offers no equivalent instant-withdrawal option.
| Settlement Option | PayPal Pay Later |
| Balance credit | Minutes |
| Bank withdrawal (free) | 1–3 business days |
| Instant transfer | Minutes (1.75% fee, $25 cap) |
Supported Payment Methods. PayPal offers a variety of payment options, including cards, Venmo, wallet balances, invoicing, checkout links, and Zettle POS hardware, in addition to the two installment products that can be used in-store through a single-use virtual card. The Payouts API supports mass payouts of up to 15,000 transfers per API call across 24 currencies and 200+ markets. PayPal is also the only incumbent here with live stablecoin rails: PYUSD holds roughly $2.7 billion in supply across 70+ markets, and “Pay with Crypto” supports 100+ cryptocurrencies at about 1.5% for US merchants.
| Feature | PayPal Pay Later |
| Pay in 4 | ✅ |
| Mass payouts | ✅ |
| Venmo / wallet | ✅ |
| Stablecoins | PYUSD |
Why Choose PayPal Pay Later Over Sezzle:
For a merchant already paying PayPal rates, moving BNPL volume from Sezzle to PayPal Pay Later lowers the fee from 6.1% + $0.30 to 4.99% + $0.49, adds a minute-level instant-transfer option, and requires no new integration or reconciliation flow. Pay in 4 carries zero consumer fees, cutting the complaint categories that BNPL fee schedules create. The caution flag is consumer sentiment: the platform’s Trustpilot score sits at 1.3–1.5/5, dominated by account-freeze reports.
Sources:
Zip
Best for: reaching credit-invisible US consumers in everyday spending categories.
Zip is an independent BNPL provider listed on the ASX. A proposed merger with its main North American rival was agreed to in February 2022 and terminated in July 2022, and the two remain separate companies. Zip posted its first annual profit in fiscal 2025, with A$13.1 billion in total transaction volume, 6.3 million active customers, including 4.25 million in the US, and 93 million transactions across 85,500 merchants. Its audience concentrates among consumers underserved by traditional credit and shopping categories like groceries, health, and education. Among Sezzle like apps, it is one of the few that publishes its merchant rate card.
Transaction Fees. Zip publishes US pricing openly: from 5.9% + $0.30 per transaction, with no monthly or annual fees and custom enterprise pricing above standard volume. Consumers may pay an origination fee ranging from $0 to $124, depending on the purchase amount and repayment plan. This fee is disclosed as a finance charge.
| Transaction Type | Zip |
| Published US rate | from 5.9% + $0.30 |
| Consumer late fee | Up to $7 |
| Pricing format | Public rate card |
Transaction Speed. Zip pays merchants the full order value upfront minus fees, settling in typically 1–2 business days, within two banking days through its Mint Payments partnership, or on standard Stripe timing when enabled via the Dashboard. Shoppers can use Pay in 4 over six weeks, Pay in 8, or the newer Pay in 2, with every purchase individually approved at checkout. Settlement beats Sezzle’s one-to-seven-day window at both ends of the range.
| Settlement Option | Zip |
| Payout timing | 1–2 business days |
| Stripe-rail timing | Standard Stripe payout |
Supported Payment Methods. Zip operates online, in-app, and in-store (in-store represents 23% of US volume, growing 65% year over year) through a virtual card in the Zip app, Apple Pay, and Google Pay in the US. Developers get a public API with Express Checkout and webhooks. Merchants can activate Zip without code through the Stripe Dashboard, with plugins for Shopify, BigCommerce, WooCommerce, and Magento.
| Feature | Zip |
| Plan types | Pay in 2 / 4 / 8 |
| In-store share (US) | 23% of volume |
| Stripe no-code setup | ✅ |
| Active customers | 6.3M |
Why Choose Zip Over Sezzle:
Zip marginally undercuts Sezzle on price, 5.9% versus 6.1% at the entry tier, while beating it on settlement speed, published pricing, and consumer fee caps: its late fee maximum of $7 is less than half as high. Trustpilot sentiment is strong at roughly 4.9/5 across about 27,000 reviews, though coverage is limited to the US and Australia, with New Zealand winding down.
Sources:
Splitit
Best for: high-AOV purchases split across a shopper’s existing credit line, with no new credit application.
Splitit approaches installments differently from loan-based BNPL providers: it splits the purchase across the shopper’s existing Visa or Mastercard credit line instead of issuing a new loan. There is no credit check, no application, no interest, and no fees from Splitit. The merchant gets white-label, on-site installments while keeping full ownership of customer data. Average order values run $1,200+ with approval rates above 85%. For shoppers fatigued by fees and declined applications, Splitit removes both friction points.
Transaction Fees. Splitit does not publish a flat rate card. Pricing is package-based, typically 1.5%–6.5% plus a flat per-transaction amount, with upfront-settlement packages costing more than installment-aligned payouts. One published data point shows 1.5% + $1.50 per installment, and setup plus integration are free. The pricing page references a $30 million minimum in annual sales, positioning the platform toward established businesses.
| Transaction Type | Splitit |
| Merchant fee | ~1.5%–6.5% + flat (package) |
| Consumer fees | $0 |
Transaction Speed. Merchants choose their funding model: receive 100% of the purchase amount upfront at the moment of sale, or receive funds in line with the shopper’s repayment cadence at a lower package rate. Bank settlement follows in 1–2 business days either way. Shoppers repay across 2–12 installments, with partner plans extending to 24–36 months and a “Pay After Delivery” option stretching to 90 days.
| Settlement Option | Splitit |
| Funding model | Upfront OR installment-aligned |
| Bank settlement | 1–2 business days |
Supported Payment Methods. Splitit works with existing Visa and Mastercard credit lines, supports splitting an order across two cards, and releases its pre-authorization hold when the final installment clears. In-store checkout runs through Samsung Wallet NFC, added in July 2025, alongside phone and offline orders. The developer platform offers a Direct API with SDKs and plugins for Shopify Plus, WooCommerce, Magento, BigCommerce, Salesforce Commerce Cloud, Wix, and SAP Commerce Cloud.
| Feature | Splitit |
| New credit line required | uses existing card line |
| White-label checkout | ✅ |
| Average order value | $1,200+ |
Why Choose Splitit Over Sezzle:
Splitit eliminates the two things shoppers dislike most about BNPL (credit applications and late fees) while giving merchants a funding choice Sezzle does not offer. Approval rates exceed 85% with zero credit-score impact, and the white-label flow keeps shoppers on the merchant’s site under the merchant’s branding.
Sources:
Sezzle Alternative Fees Compared
Advertised rates do not provide a complete picture. Fixed per-transaction charges, minimum monthly fees, and payout timing all affect what a merchant actually pays. The table below shows the standard fee and the estimated total cost on a $100 same-currency sale.
| Solution | Standard Fee | Fixed Fee | Total Cost Example ($100) |
| NOWPayments | 0.3%–1.5% | $0 | ~0.30-1.50 |
| Splitit | 1.5%–6.5% | Flat per installment | ~$1.50+ |
| Klarna | ~3–6% | ~$0.30 | ~3.30-6.30 |
| Affirm | ~3–6% | ~$0.30 | ~3.30-6.30 |
| Afterpay | 4–6% | $0.30 | ~4.30-6.30 |
| PayPal Pay Later | 4.99% | $0.49 | ~$5.48 |
| Zip | from 5.9% | $0.30 | ~$6.20 |
| Sezzle | 6.1% | $0.30 | ~$6.40 |
*Rates are based on publicly available pricing pages and may vary by volume, verification level, payment method, and settlement route. Verify current fees directly with each provider.
One pattern emerges when companies like Sezzle and its rivals sit side by side. Splitit’s package pricing can undercut every loan-based provider when merchants accept installment-aligned funding, while its 6.1% standard sits at the top of the table before the $15 monthly minimum is counted.
BNPL Lenders vs. Payment Infrastructure
The seven options split into two operational models, and matching the model to the business problem matters more than any single fee percentage.
| Model | Providers | Who Funds the Shopper | Payout Control | Geography |
| BNPL / installment lender | Klarna, Afterpay, Affirm, Zip, Splitit | Provider’s credit book or shopper’s card line | Provider’s schedule (1–3 business days typical) | US/Canada, or US/EU/AU for the largest |
| Payment infrastructure | NOWPayments, PayPal | Shopper’s own funds (no credit issued) | Merchant wallet, custody account, or bank | Global, or 200+ markets |
Loan-based BNPL lifts conversion by funding the shopper, but it costs 4–6%+ per transaction, caps order sizes, and settles on banking timelines. For buy now pay later like Sezzle arrangements, the lender model is the only option; the infrastructure model replaces the credit function rather than replicating it.
How to Choose the Best Sezzle Alternative
Before switching, compare providers on the criteria that affect daily operations:
- Fees: published rate card or quote-based, fixed per-transaction charges, and minimum monthly fees.
- Payout speed: standard settlement timing and whether an instant option exists.
- Payment methods: cards, installment plans, stablecoins, and cryptocurrencies.
- Credit model: new loan per order, existing card line, or no credit at all.
- Geography: markets covered for both merchant settlement and shopper eligibility.
- Payout tooling: mass payouts, email payouts, custody balances, and treasury workflows.
- Risk policy: reserves, fund holds, prohibited categories, and account-freeze history.
- Support quality: response times, availability windows, and dedicated account management.
When to Choose Each Sezzle Competitor: Decision Framework
Choose NOWPayments if you:
- want stablecoin settlement in USDT and USDC.
- need support for Ethereum, Tron, BSC, Polygon, and other networks.
- need mass payouts for affiliates, creators, or contractors.
- prefer email-based payouts.
- operate across international markets.
- want payments, conversions, custody, and treasury in one ecosystem.
- need compliance guidance and tax documentation support.
Choose Klarna if you:
- sell across multiple international markets.
- need BNPL coverage in 26 markets.
- want Pay in 4, Pay in 30, and longer-term financing.
- prefer several installment plans through one integration.
Choose Afterpay if you:
- target US Gen Z and millennial shoppers.
- want access to a large BNPL customer network.
- already use Square, Stripe, or Adyen.
- prefer activation without adding a new payout rail.
Choose Affirm if you:
- sell higher-ticket products.
- need financing terms from 3 to 60 months.
- offer purchases up to $25,000+.
- use Shopify and want Shop Pay Installments.
Choose PayPal Pay Later if you:
- already accept PayPal.
- want BNPL without an additional integration.
- prefer pricing of 4.99% + $0.49.
- need instant-transfer payouts.
- want access to a mass-payout API.
Choose Zip if you:
- target US shoppers with limited credit histories.
- sell everyday products, including groceries and health items.
- prefer published merchant pricing.
- want rates starting at 5.9% + $0.30.
Choose Splitit if you:
- sell high-value products.
- have an average order value above $1,200.
- serve customers with existing credit cards.
- want installments without credit checks.
- prefer no interest or provider fees for shoppers.
Stick with Sezzle if you:
- primarily sell in the US or Canada.
- serve shoppers interested in credit building.
- want access to the Sezzle Up program.
- consistently exceed $300 in monthly order volume.
- can comfortably absorb the $15 monthly minimum fee.


Be the first to comment