

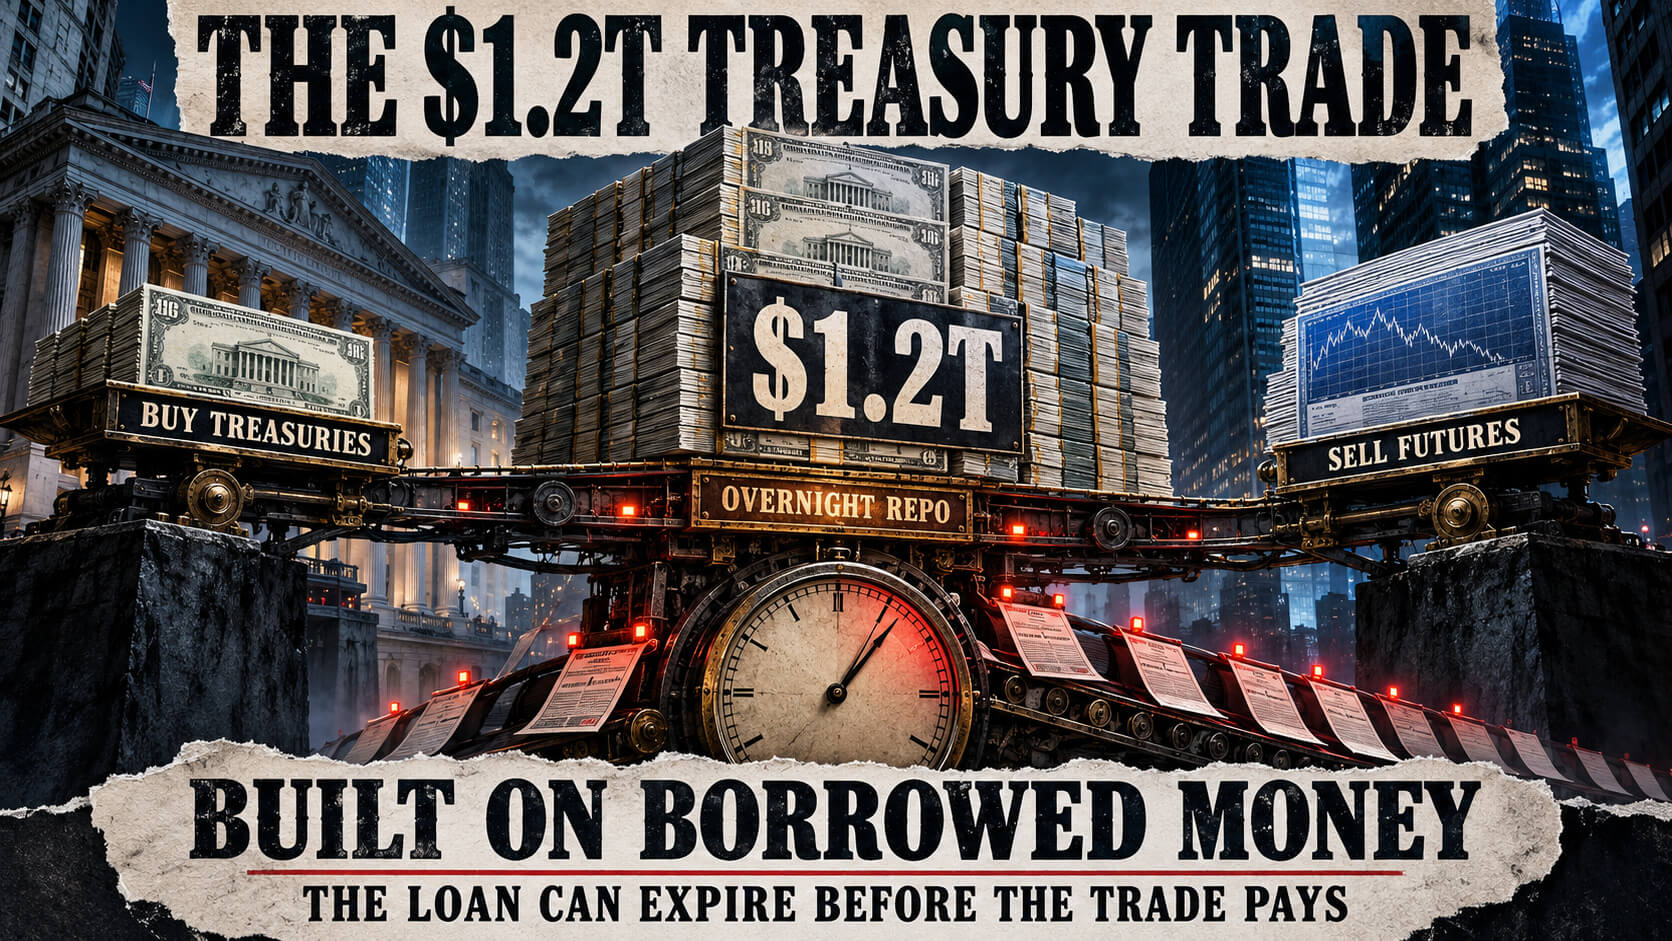
Companies can own a mountain of US government debt without betting that bond prices will rise. Hedge funds buy Treasury securities and sell futures against them to collect a small pricing gap, borrowing most of the purchase money to make the return worthwhile.
The government gets another buyer, whose interest lasts as long as the trade pays.
The catch is that the loan can expire tomorrow while the trade needs longer to pay off. The government’s ability to repay its debt doesn’t solve the fund’s need to repay its lender.
This is the Treasury cash-futures basis trade, and the sums involved are large enough to reach well beyond the bond desk. Morgan Stanley estimated positions had fallen 20% this year to about $1.2 trillion, according to Sept. 24 reports.
The bank hadn’t found evidence of broad basis-related market stress at that point, so a smaller trade wasn’t automatically a trade that would blow up.
Hedge funds love small profits when it’s someone else’s money
You can buy a Treasury security outright, or trade a futures contract that sets terms now for a transaction completed later. The contract specifies which securities can be delivered against it, linking their prices without making them identical.
When futures are expensive enough relative to an eligible bond, the fund buys the bond and sells the futures. Investors wanting bond-market exposure through contracts supply the other side, leaving the fund to hold the actual securities.
Selling the futures is the hedge: if bond prices fall, that short position can earn money that offsets much of the loss on the bond. The fund aims to collect the pricing gap as the contract approaches delivery, while limiting its exposure to the market’s overall direction.
To pay for the bond, it uses repo, short for repurchase agreement. The fund sells the security for cash and agrees to buy it back later at a slightly higher price, which, economically speaking, looks like a loan secured by the bond.
Overnight repo means the fund must renew or replace the financing to keep the position.
Consider an illustrative $100 million position earning 0.2% annually from the strategy, net of assumed financing and trading costs. That’s $200,000, which becomes a 4% return if the fund has committed only $5 million of its own capital.
But if borrowing costs on the other $95 million increase by 0.2% for the year, the extra bill is $190,000. Almost the entire expected profit has gone to the lender, without the government defaulting on anything.
The Office of Financial Research includes the cost of futures margin and the seller’s options over which eligible bond to deliver and when. Calculating the return means valuing those delivery rights and accounting for financing and margin costs.
If that calculation stops looking attractive, a fund can simply stop replacing positions as they expire. Professional investors don’t need a crisis to find something better to do with their money.
Being right doesn’t pay today’s bill
The hedge may work, but the fund can’t afford the payments needed to keep it open.
Suppose the bond gains value and the short futures position loses a similar amount. The futures account can require a cash payment against that loss, known as variation margin, while the bond’s gain is still tied up in a security.
The fund has to get dollars out of that asset or find them elsewhere before the payment is due.
Crypto traders with gains on one exchange and a liquidation approaching on another will recognize the problem: money in the wrong account won’t meet the payment, and explaining the hedge won’t extend the deadline.
The repo lender can also require more money. If it lends $98 against $100 of bonds, the fund supplies the other $2, a 2% haircut. If that haircut becomes 4%, the fund must supply twice as much of its own money against the same collateral, even before considering futures margin.
If many funds have to close positions at the same time, they sell bonds to repay loans and buy futures to close their shorts. Those trades can push bond prices down relative to futures, hurting funds still holding the same positions and making their own exits more expensive.
That forced selling is different from letting trades expire without replacing them, although both reduce outstanding positions. The reported contraction alone won’t tell you which is happening.
Federal Reserve researchers estimated $830 billion of basis positions for September 2025, in research published this June. That and Morgan Stanley’s newer estimate use different approaches, so treating them as consecutive readings would manufacture a comparison the data doesn’t support.
Total hedge-fund Treasury holdings also include other strategies, as do their short futures positions.
Someone still has to own the Treasury bonds
Fewer trades dependent on tomorrow’s loan can make the market less fragile, provided the next owners bring financing they can keep through a difficult week. Investors buying with committed capital don’t face the same daily negotiation with a repo lender.
Those buyers may want a better price because they’re buying the bond for its income. Cheaper bonds offer higher yields, attracting replacement demand while potentially making new government borrowing more expensive.
Dealers can hold bonds while they find buyers, but their capacity also costs money and has limits. An orderly transfer can therefore leave Washington paying more without the market breaking down.
Higher repo rates or larger haircuts become more troubling if funds must sell into a market with few willing buyers. Those financing terms and the prices sellers can obtain say more about stress than a position total alone.
The same restraint applies to Bitcoin, as hedge funds’ broader balance sheets show why one strategy can’t stand in for everything those firms do.
Connecting Treasury trouble to crypto requires evidence that the institutions involved are selling crypto or withdrawing financing, rather than assuming every cash need ends with a Bitcoin sale.
Borrowed money makes these funds willing to own bonds for a return that would otherwise be too small to bother with.
When that calculation stops working, replacing them can reduce the market’s dependence on overnight loans, but the next owner may want a higher yield to take the debt off their hands.


Be the first to comment