


AI Summary
- Franklin Crypto’s institutional thesis extends beyond holding Bitcoin to using public blockchains as market infrastructure.
- Native gas tokens could acquire strategic utility if substantial financial activity moves onto Ethereum, Solana and other public networks.
- Tokenized money markets may offer more useful collateral than non yielding stablecoins, but adoption still depends on practical integrations.
- Quantum computing remains a material risk, although crypto’s incentive to adopt postquantum cryptography could make the industry an early mover.
- Institutional adoption will depend on controls, standardization and demonstrable token value accrual rather than broad altcoin exposure.
The common institutional crypto narrative still begins and ends with Bitcoin exposure. The more consequential possibility is that financial institutions may eventually need blockchain assets for operations, not merely portfolio allocation. That distinction could reshape how investors assess Ethereum, Solana and other networks supporting tokenized markets.
Franklin Templeton has been developing its crypto initiative since 2017, according to Chris Perkins, head of Franklin Crypto. Perkins said the asset manager runs multiple validators and has invested in relevant infrastructure and ecosystems. His central thesis is that native gas assets could become strategically important if equities, stablecoins and other real world assets migrate onto public networks.
That is a conditional investment case, not proof that every layer one token will accrue value. Our analysis is that the thesis depends on three unresolved questions: whether activity settles on public blockchains, whether network usage creates durable demand for gas tokens, and whether institutions can control custody, regulatory and cyber risks at scale.
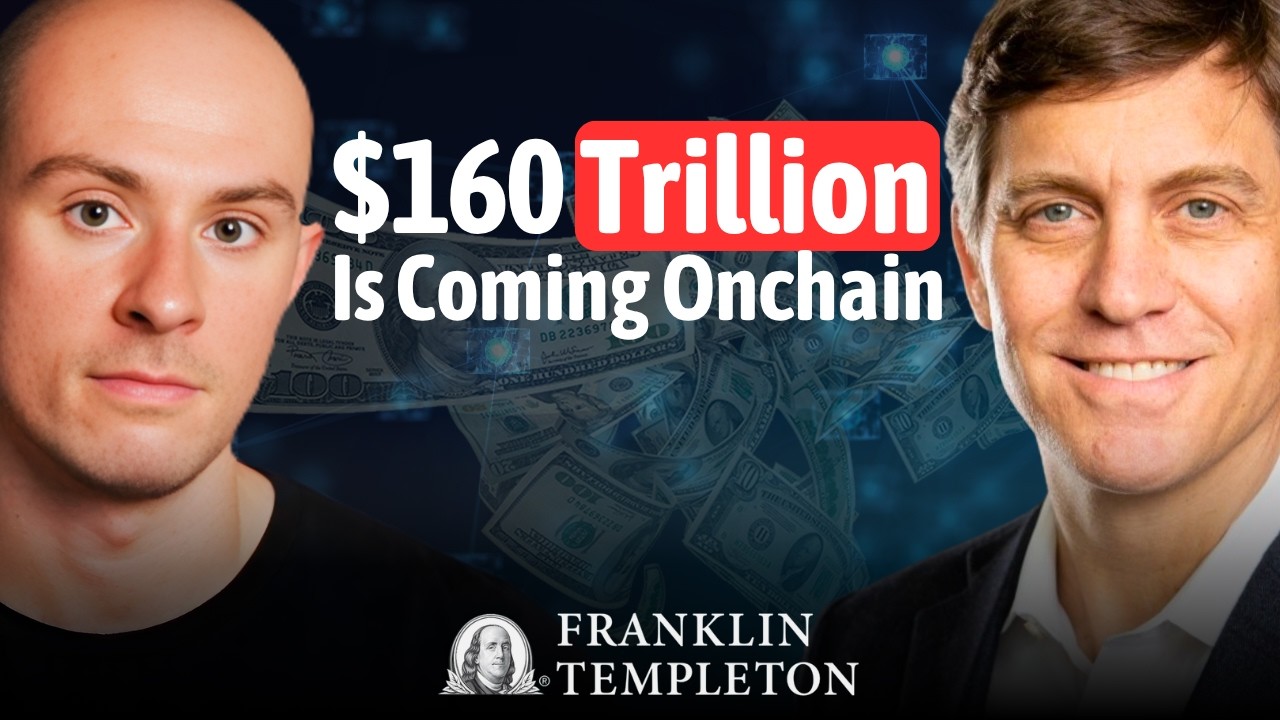
Wall Street Needs These Crypto Tokens To Unlock The Future With Franklin Crypto
Institutional demand is shifting from exposure to infrastructure
Perkins described a change in institutional conversations. Where boards and regulators previously rewarded firms for avoiding crypto, clients are now asking what their organizations are doing in the sector. Franklin Crypto is responding with active strategies spanning liquid markets, venture investments and exploratory private credit concepts, while expanding its team and consolidating internal capabilities.
The important signal is not a forecast about near term token prices. It is the move from passive curiosity toward products, controls and operating infrastructure. Institutions generally accept market risk when it can be measured, but reputational, regulatory, operational and cyber risks can prevent an allocation before valuation even enters the discussion.
- People: Franklin Crypto is hiring and organizing a dedicated active management operation.
- Products: Its stated scope includes open ended, closed ended, liquid and venture strategies.
- Controls: Legal, compliance, operational risk and cybersecurity functions remain central to institutional deployment.
- Infrastructure: Franklin Templeton’s validators represent direct participation in selected blockchain ecosystems.
We see this as evidence of institutional preparation rather than confirmation of mass adoption. Building capacity can precede demand by years, and not every product will attract sufficient capital. Even so, the breadth of the work suggests that large asset managers increasingly view crypto as a market structure question rather than one isolated speculative trade.
Bitcoin remains the anchor but not the complete thesis
Perkins characterized Bitcoin as a powerful store of value with a known issuance limit and greater portability than physical gold. He also acknowledged security concerns, custody requirements and uncertainty around quantum computing. This produces a more defensible institutional case than treating Bitcoin as either risk free or obsolete.
“I’m not a Bitcoin maximalist. I’m a fundamental maximalist. I’m a utility maximalist.”
The distinction matters for the wider market. Bitcoin’s monetary proposition does not automatically validate every alternative asset, while the utility of programmable networks cannot be assessed through Bitcoin’s scarcity framework alone. Tokens tied to settlement, computation or collateral systems require their own underwriting models.
Perkins said allocation size must depend on each client’s objectives and risk tolerance, even noting that some portfolios might justify a higher allocation than others. That restraint is important. Recent AllinCrypto analysis has shown how the Bitcoin thesis remains exposed to policy and interest rate tests, while a separate examination considered the interaction between Bitcoin, Treasury demand and stablecoin growth.
Tokenized markets make network gas strategic
The strongest part of the public blockchain utility thesis concerns access. A conventional exchange traded fund places an asset inside familiar securities infrastructure, including brokerage and financing arrangements. A token can instead provide continuous market access, programmability and composability. These formats are wrappers with different capabilities, and institutions may use both.

“The beautiful thing about crypto is that it unlocks new forms of utility. Real time atomic global settlement. No-brainer.”
If tokenized equities and other assets settle on public chains, participants may need the native asset to execute transactions. Perkins named Ethereum, Solana and Avalanche among examples of networks with different capabilities and limitations. Stellar was also raised in the discussion as an example of a network associated with real world usage.
- Settlement demand: Network tokens may be needed to pay for transactions and finalize transfers.
- Operational reserves: Institutions may hold gas in advance if access during volatile periods is essential.
- Programmability: Tokenized assets can support automated movement, composability and more continuous risk management.
- Value accrual: Usage matters only if demand reaches the native token under the network’s actual economic design.
The last point prevents the thesis from becoming a blanket endorsement. High transaction volume does not necessarily produce proportionate token value, and networks can modify fee mechanisms. Applications may also abstract gas from end users or adopt dollar based payment models. The relevant analysis therefore runs from asset activity through fee design to measurable token demand.
“If these markets migrate on chain, then of course it’s a no-brainer.”
Stablecoins and tokenized money markets serve different needs
Stablecoins offer rapid transfer of dollar denominated value, but Perkins questioned why users with access to stronger alternatives would hold a non yielding instrument for long periods. He distinguished their payment function from tokenized money markets, which can return yield to the holder while remaining available for financial activity.
The practical constraint is utility. A payment asset becomes more useful when it can purchase goods, acquire financial instruments or move seamlessly into collateral workflows. Perkins noted that, in his experience, even buying a US Treasury directly with a stablecoin remained difficult. His view was that stablecoins already have a clearer proposition where access to dollars is limited, while broader adoption needs better endpoints.
- Payments: Stablecoins prioritize transferable dollar value and continuous availability.
- Store of value: Tokenized money market assets can preserve exposure while directing yield to the holder.
- Collateral: A yielding asset may remain productive while supporting derivatives or other obligations.
- Capital efficiency: Faster settlement could reduce the buffer required for periods when conventional markets are closed.
Perkins cited large collateral pools in cleared and uncleared derivatives and argued that continuous settlement could reduce both margin requirements and risk. Those figures and outcomes were his estimates, not independently supplied data. The underlying logic is nevertheless significant: shorter settlement intervals can reduce the time during which counterparties remain exposed, provided the tokenized system itself is reliable.
Standardization will determine whether tokenization reaches scale
Perkins compared tokenization with containerized shipping and standardized derivatives. His point was that a common format can turn bespoke processes into repeatable, high volume infrastructure. In crypto, token standards and interoperable systems could play that role, although bridges and other cross network mechanisms introduce their own security concerns.
Standardization also changes industry economics. Perkins expects regulation to impose fixed compliance costs while comparable products face fee pressure. Scale then becomes more important, potentially causing consolidation among centralized service providers even while underlying protocols remain distributed.
This tension deserves attention. Institutional controls can broaden participation, but concentrated custody, execution or compliance services can create dependencies around decentralized networks. The winning architecture may combine open settlement with regulated access points rather than delivering a pure version of either centralized finance or crypto native markets.
Quantum risk could become an adoption catalyst
Quantum computing is usually presented as an existential threat to blockchain signatures. Perkins accepts the threat but offers the opposite medium term interpretation: because cryptography is fundamental to the industry, crypto networks have unusually strong incentives to develop and implement postquantum cryptography.
“Crypto is like existential for us.”
He cited uncertain estimates placing a potential cryptographic breaking point around 2030 or 2035 and argued that artificial intelligence could accelerate development. These dates are guest scenarios, not established deadlines. Migration remains difficult because security upgrades must protect existing assets, preserve compatibility and achieve coordination across users, developers and infrastructure providers.
“decentralization is always more resilient. Maybe not the most efficient, but definitely the most resilient.”
Our view is that quantum readiness should be treated as a testable engineering and governance capability, not an automatic bullish catalyst. A network that demonstrates credible migration procedures could gain institutional confidence. One that merely invokes resilience without shipping protections would leave the core risk unresolved.
What this means
-
Utility must become observable. The credible altcoin thesis is not that every network benefits from tokenization. It is that specific activity creates recurring demand for settlement, security or gas under a transparent economic model.
-
Infrastructure can matter more than initial allocation. Validators, custody, controls and tokenized collateral systems may reveal institutional commitment before large directional positions appear in public view.
-
Risk reduction is the decisive test. Continuous markets are valuable only when operational, cyber, legal and liquidity risks are controlled. Faster settlement cannot compensate for fragile bridges, uncertain permissions or poorly designed token economics.
Perkins also offered a constructive market view and said he believed the cycle was bottoming, while explicitly expecting future volatility. We treat that as an attributed forecast. The deeper institutional case does not require a near term market bottom; it requires tokenized systems to deliver better settlement and collateral outcomes over time.
Bigger picture
Recent developments covered by AllinCrypto provide context for the thesis without proving it. DTCC’s planned phased tokenized asset rollout on Stellar places settlement controls and network choice inside an institutional implementation. A separate Hanwha Securities platform on Avalanche illustrates how another public network is being positioned for tokenization.
The policy layer remains unsettled. Perkins called the CLARITY Act a solid but imperfect bill and argued that regulatory guidance could still provide a workable path if Congress did not enact it. That view should be weighed against AllinCrypto’s reporting on low legislative odds and narrower regulatory relief.
We therefore see a sequence rather than a single catalyst: regulation defines permissible activity, standards lower integration costs, infrastructure controls operational risk, and actual usage determines whether tokens accrue value. The case for Ethereum, Solana and their competitors becomes stronger only as each link in that chain produces evidence.
Sources
This article is for informational purposes only and does not constitute financial advice.


Be the first to comment