


- The Australian Financial Complaints Authority said on 1 October that users of cryptocurrency, stablecoins, wrapped tokens, tokenised securities and digital asset wallets can bring unresolved disputes to it where the firm is a member.
- AFCA’s release lists 67 digital asset businesses as members, including Coinbase Australia, Kraken’s Bit Trade, Swyftx, CoinSpot and Binance Australia.
- ASIC’s no-action letter required retail-facing digital asset firms to join AFCA before lodging licence applications by 30 September; firms that missed the deadline risk fines of up to 10% of annual turnover.
Australians using crypto, stablecoins or tokenised securities can now take disputes to the Australian Financial Complaints Authority (AFCA) if their provider is a member, the ombudsman said on 1 October.
AFCA membership was voluntary for digital asset firms until ASIC clarified in October 2025 which digital assets count as financial products under the Corporations Act. A business that provides services involving financial products generally needs an Australian Financial Services Licence and must belong to AFCA.
AFCA’s release lists 67 firms providing digital asset services as members. They include Coinbase Australia, Kraken’s Australian arm Bit Trade, Swyftx, CoinSpot operator Casey Block Services, Binance Australia operator Investbybit and Crypto.com’s Foris Dax. Consumers can check whether a platform is a member through AFCA’s find-a-financial-firm tool. They must first try to resolve the matter directly with the firm.
“This requirement gives consumers a clear pathway to complain if they are using these products and something goes wrong,” AFCA’s lead ombudsman for investments and advice, Shail Singh, said.
Read more: Standard Chartered Starts Research Coverage for Ethena
ASIC’s class no-action letter gave digital asset businesses until 30 September to lodge an application for a licence. To rely on the letter, a firm serving retail clients had to join AFCA before lodging. It must then stay a member for at least a year after it stops using the relief.
ASIC set the original 30 June deadline when it updated its crypto licensing guidance in October 2025, then extended it by three months on 25 June.
On 2 September the regulator issued a final call before the deadline, saying it had received more than 45 licence applications since the update. Firms that needed a licence but missed the cut-off now risk civil and criminal penalties, including fines of up to 10% of annual turnover.
More Than 1,000 Complaints Already
Singh said AFCA has handled more than 1,000 complaints about digital assets over the past six years. AFCA said last October that it received 159 complaints in 2024-25 about cryptocurrency firms that were voluntary members.
Scams, the interpretation of product terms and failures to act in a client’s best interest were the most common issues in those complaints. Where the parties cannot agree, AFCA can issue a decision that binds the firm.
Digital assets are increasingly part of the way people manage and move money, so it’s important consumers have access to independent dispute resolution service if they need it.
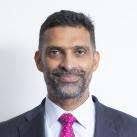 AFCA’s lead ombudsman for investments and advice, Shail Singh
The Corporations Amendment (Digital Assets Framework) Act 2026, which sets new crypto rules for exchanges and custodians, passed Parliament on 1 April and takes effect on 9 April 2027.
Read also: XRP Ledger Expands in Brazil With $6 Trillion Market Infrastructure Operator


Be the first to comment